Our team views indoor air quality (IAQ) as an operational attribute of buildings that belongs in environmental, social and governance (ESG) reporting. Investors, occupiers and regulators are moving beyond high level sustainability claims to expect measurable management of the built environment. Integrating IAQ into ESG disclosures helps demonstrate duty of care, protects asset value and turns an invisible risk into an auditable management issue.
This introduction gives practical advice on what belongs in an IAQ metric set, how to collect trustworthy data, and how to present IAQ within governance and assurance frameworks used for ESG reporting.
Why indoor air quality belongs in ESG
Indoor air quality touches all three pillars of ESG. It sits within the environmental dimension when links to building energy, ventilation and filtration are disclosed. It is a core social consideration because IAQ affects occupant health, comfort and productivity. It also belongs under governance where monitoring policies, maintenance regimes and assurance procedures are documented.
ESG frameworks such as the Global Reporting Initiative (GRI) and the Sustainability Accounting Standards Board (SASB) emphasise material risks and stakeholder health. For many organisations, IAQ is a material operational risk: poor ventilation can create complaints, increase absence and reduce productivity, while good IAQ is a demonstrable element of responsible asset stewardship.
Key IAQ metrics to include in reporting
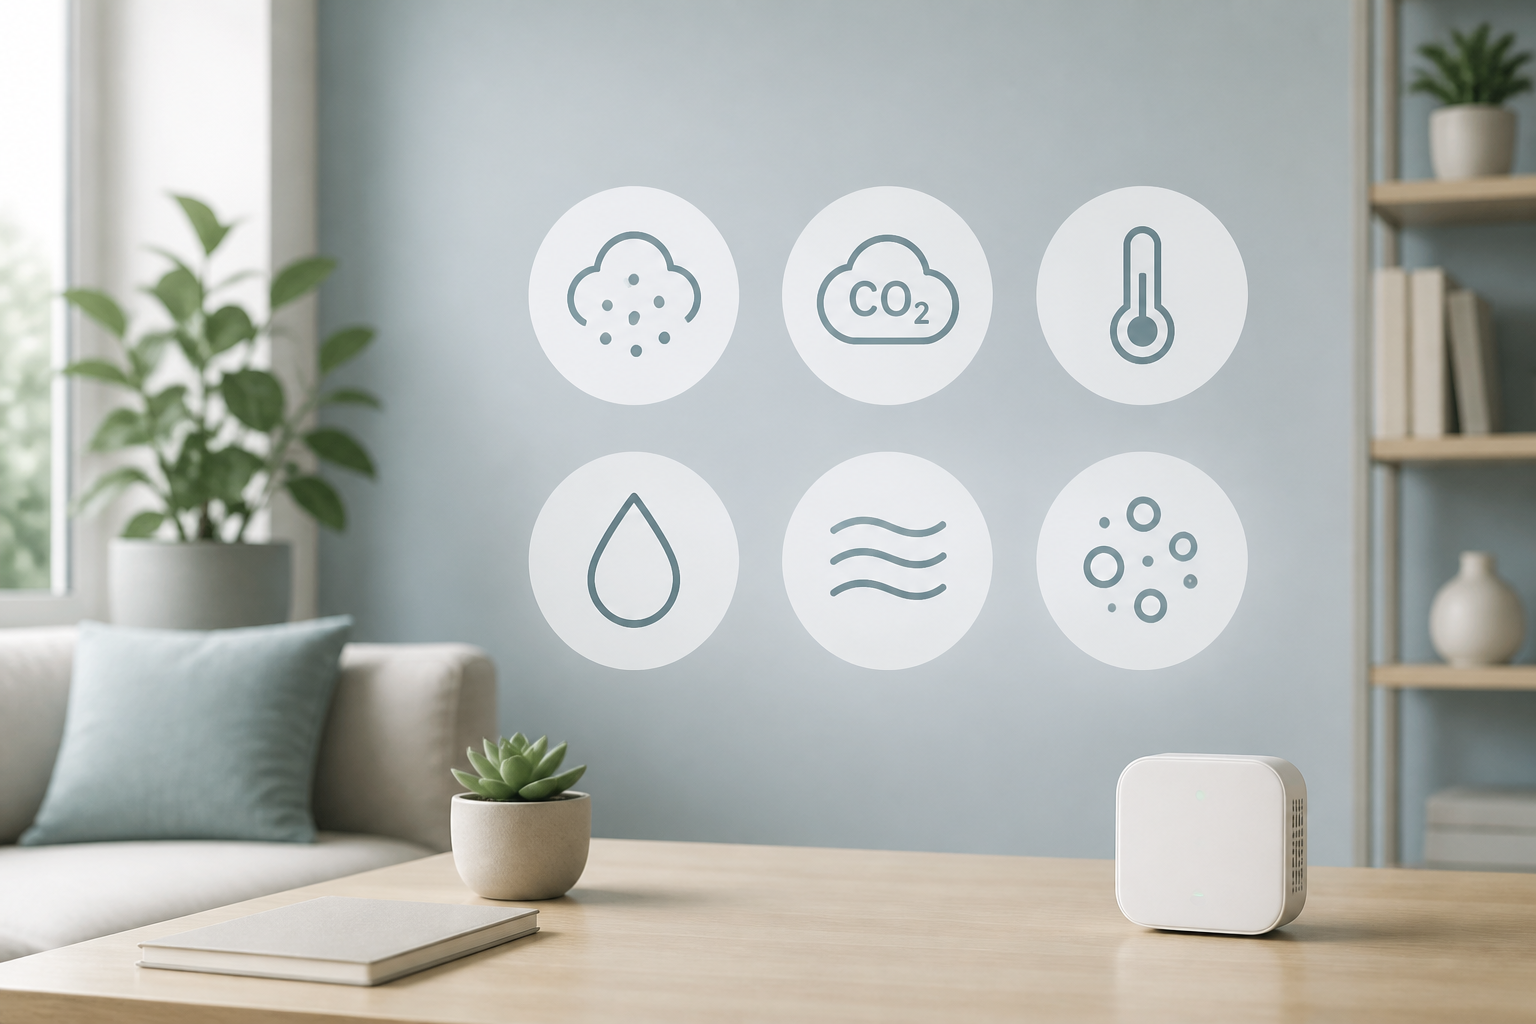
Choose metrics that are measurable, comparable and relevant to your portfolio. Typical IAQ indicators used in corporate reporting include:
- CO2 concentration as a proxy for ventilation adequacy and occupancy-related risk.
- Ventilation rate estimates expressed per person or per square metre, where direct airflow measurements or system data are available.
- Particulate matter such as PM2.5 and PM10 when outdoor or indoor combustion sources are relevant.
- Volatile organic compounds (VOCs) when emissions from materials, fit-out or cleaning are a concern.
- Relative humidity and temperature which influence comfort, mould risk and HVAC performance.
- Hygiene and maintenance indicators such as ductwork cleanliness (for example referencing TR19 guidance where applicable) and filter replacement records.
Present metrics with clear context: include the measurement period, occupied hours, whether values are averaged, and any normalisation by occupancy or operating hours. Raw concentrations matter less than compliance with agreed thresholds and trends over time.
How to collect robust IAQ data
Reliable IAQ reporting depends on data quality, comparability and traceability. Consider three complementary approaches:
- Continuous monitoring using calibrated sensors for CO2, PM and temperature/humidity. Continuous data reveal daily patterns, peak exposures and system failures.
- Planned spot testing for VOCs and detailed particulate characterisation where continuous sensors are not practical. Spot tests are valuable for due diligence and forensic investigation.
- System-based indicators from building management systems (BMS) such as supply air volumes, fan runtimes and filter pressure drops, which help translate indoor concentrations into operational performance.
Data governance essentials include sensor calibration schedules, defined data retention periods, and a single source of truth for IAQ metrics. Normalise results for occupancy and hours of operation to make portfolio comparisons meaningful. Independent verification and sensor calibration are recognised best practice when IAQ is presented in formal ESG disclosures.
Reference to technical guidance from CIBSE on ventilation and monitoring is useful when designing measurement programmes, and TR19 remains the appropriate reference for ductwork cleanliness where applicable.
Governance, assurance and business implications for IAQ
Position IAQ within your organisation's materiality assessment and governance structures. That includes documented policies for monitoring, escalation pathways for exceedances, and clear ownership for remedial action. Link IAQ metrics to maintenance schedules, capital planning and occupational health records.
Assurance improves credibility. ESG auditors and investors increasingly expect evidence of third-party oversight, whether independent sensor audits, laboratory validation of spot tests, or assurance of the underlying data processing. Where IAQ metrics affect reported outcomes for health or energy use, describe the assurance approach in the narrative supporting the ESG disclosure.
Business implications are concrete. Effective IAQ management reduces complaint handling and legal risk, supports occupier retention, and protects productivity. Poor IAQ, left unmeasured, can become a slow, invisible liability that affects reputation and asset value. Framing IAQ as a measurable part of ESG transforms it from a reputational exposure into a managed operational attribute.
Key takeaways for IAQ in ESG reporting
- IAQ belongs in ESG because it intersects environmental performance, occupant wellbeing and governance of building services.
- Report a focused set of metrics: CO2, ventilation performance, particulates, VOCs, humidity and hygiene indicators where relevant.
- Use a mix of continuous monitoring, targeted spot tests and system data, and normalise for occupancy to enable comparison.
- Embed IAQ in materiality assessments, document governance and seek independent assurance for credibility.
- Good IAQ reporting shifts the conversation from vague claims to auditable building management that protects people and assets.